 NovaVida
Benefits Your People Notice. At A Cost You Can Defend.
Group medical is heading for its steepest increase since 2003. We quote the carriers we're appointed with in your state — fully insured, level-funded, ICHRA — and layer dental, vision, life, disability, voluntary benefits and a compliant Section 125 plan on top, so the renewal stops being a surprise.
Licensed in all 50 states + DC · Carriers pay us; you pay no fee · No obligation
| Avg family premium, 2026 (KFF) | $28,303 |
| Projected 2027 increase (Mercer, after changes) | +8.2% |
| Small-firm worker share of family premium | $9,687 (37%) |
| Avg small-firm single deductible | $2,624 |
| Employer FICA saved per $1 of pre-tax premium | $0.0765 |
| What a review costs you | $0 |
Sources: KFF 2026 Employer Health Benefits Survey; Mercer, Aug 2026; IRC §3111.
Sources: KFF 2026 Employer Health Benefits Survey; Mercer, Aug 2026; Aon, Aug 2026; WTW 2026 Best Practices survey (via Insurance Business) projects +11.1% before plan changes.
Carriers in our network
 HumanaGet a benefits review →
 UnitedHealthcareGet a benefits review →
 AnthemGet a benefits review →
 Florida BlueGet a benefits review →
 GuardianGet a benefits review →
 MassMutualGet a benefits review →
 Lincoln FinancialGet a benefits review →
 AmeritasGet a benefits review →
 Mutual of OmahaGet a benefits review →
 NationwideGet a benefits review →
 AmbetterGet a benefits review →
 MolinaGet a benefits review →
Carrier names and logos identify companies in our network; they do not imply endorsement of this site by any carrier. Group, individual (ICHRA) and ancillary availability varies by state and group size.
A 30-second explainer with music. Illustrative stock photography; figures from KFF 2026, Mercer and the IRS as cited on this site.
Every Line, One Broker, No Broker Fee To You
The Section 125 Math — Without The Gimmicks
When employees pay their share of premiums through a written Section 125 plan, those dollars skip federal income tax and 7.65% FICA for the employee, and you skip your matching 7.65% FICA on the same wages. On $120,000 of annual employee premium contributions that is roughly $9,180 back to you and $35,580 to your employees at a 22% bracket — every year, with a plan document, annual elections and testing.
What it is not: a "wellness" overlay that promises employees a raise and tax-free cash. The IRS has ruled those payments taxable wages (Groom Law Group on CCA 202323006). We walk away from those and say so on the Section 125 page.
Calculate My Savings How It WorksWhere $1 Of Pre-Tax Premium Goes
Illustrative: employee at the 22% federal bracket; FICA 7.65% each side. State income tax varies; New Jersey does not conform to §125.
Your Employer FICA Savings In Two Taps
Tap your headcount and the average monthly pre-tax premium share. Assumes 80% participation; the full calculator lets you change everything.
Employer side only: participants × monthly amount × 12 × 7.65%. Before plan-document and administration costs — the full calculator nets those out.
The Numbers Your Renewal Will Be Judged Against
Benefits Are The Retention Tool That Shows Up On A Pay Stub
What Employers Rate "Very Or Extremely Important"
Source: SHRM 2026 Employee Benefits Survey (5,472 organizations).
Voluntary Benefits Employees Are Very Or Extremely Interested In
Source: 2025 LIMRA-EY Workforce Benefits Study. Voluntary lines are employee-paid, so they add choice at no employer premium cost.
Licensed Benefits Advisors, Not A Quote Engine
NovaVida Benefits is the employer-benefits division of NovaVida Group, a licensed independent agency in West Palm Beach, Florida. We market your group to the carriers we're appointed with in your state, run the Section 125 and ACA math, and stay on the account at renewal. Ambient video is an illustrative render.
Three Weeks From Census To Decision
Census & Current Plan
Employee ages, ZIPs, tiers, your current rates and renewal letter. One spreadsheet; we handle the rest.
Market & Model
Fully insured, level-funded and ICHRA side by side, with the Section 125 savings and any §45R credit modeled on your numbers.
Decide & Enroll
You pick. We run enrollment, the plan documents, the notices and the compliance calendar.
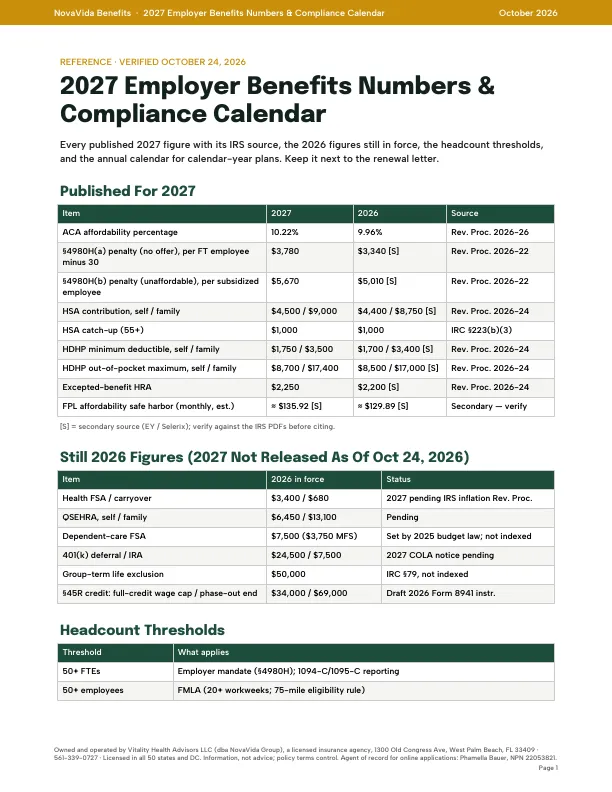
2027 Employer Benefits Numbers & Compliance Calendar
Every published 2027 figure with its IRS source, the 2026 limits still in force, the headcount thresholds and the annual calendar — two pages to keep next to the renewal letter.
- Affordability 10.22%, §4980H $3,780 / $5,670, HSA $4,500 / $9,000 and more
- Marked where a figure is secondary-sourced
- Opens instantly after you submit
Questions Employers Ask
How much does group health insurance cost per employee in 2026?
KFF's 2026 Employer Health Benefits Survey puts the average annual premium at $9,804 for single coverage and $28,303 for family coverage, with workers contributing $1,672 and $7,471. At small firms (10–199 workers) the family worker share averages $9,687 (37%). Aon's broader measure of total 2026 plan cost is $17,562 per employee.
How much will employer health costs rise in 2027?
Mercer projects +8.2% per employee after plan changes (+11% with no changes), the largest increase since 2003. Aon projects +9.5%; WTW projects +11.1% before changes and +9.7% after.
Do I have to offer health insurance to my employees?
Only if you are an applicable large employer — 50 or more full-time-equivalent employees. For plan years starting in 2027 the Section 4980H penalties are $3,780 (no offer) and $5,670 (unaffordable offer) per affected employee, per Rev. Proc. 2026-22. Under 50 FTEs, offering coverage is voluntary.
What makes coverage "affordable" under the ACA in 2027?
The employee's cost for the lowest-priced self-only plan may not exceed 10.22% of household income (up from 9.96% in 2026), per Rev. Proc. 2026-26. Employers use the W-2, rate-of-pay or federal-poverty-line safe harbors; the FPL safe harbor is roughly $135.92 a month for 2027 (a secondary-source figure — verify before relying on it).
What is a Section 125 plan?
A written plan under IRC §125 that lets employees pay for qualified benefits — health, dental, vision, group-term life up to $50,000, supplemental coverage, health FSA, dependent-care FSA — with pre-tax salary reductions. Employees avoid federal income tax and 7.65% FICA on those amounts; the employer avoids its matching 7.65% FICA (and FUTA) on the reduced wages.
Are "Section 125 wellness plans" that promise cash back and no change in take-home pay legal?
The IRS has repeatedly said the cash is taxable. Chief Counsel Advice 202323006 (2023) held that fixed-indemnity "wellness" payments funded with pre-tax premiums are wages subject to income tax, FICA and FUTA when the employee has no unreimbursed medical expense, and Treasury restated in the preamble to the March 2024 fixed-indemnity rule that existing law already denies the exclusion; IR-2024-65 warned employers again. Practitioner alerts in 2026 report promoters are still selling these arrangements. We do not offer them.
Get A Benefits Review
A licensed benefits advisor reviews your situation and comes back with options and numbers. No fee, no obligation.